


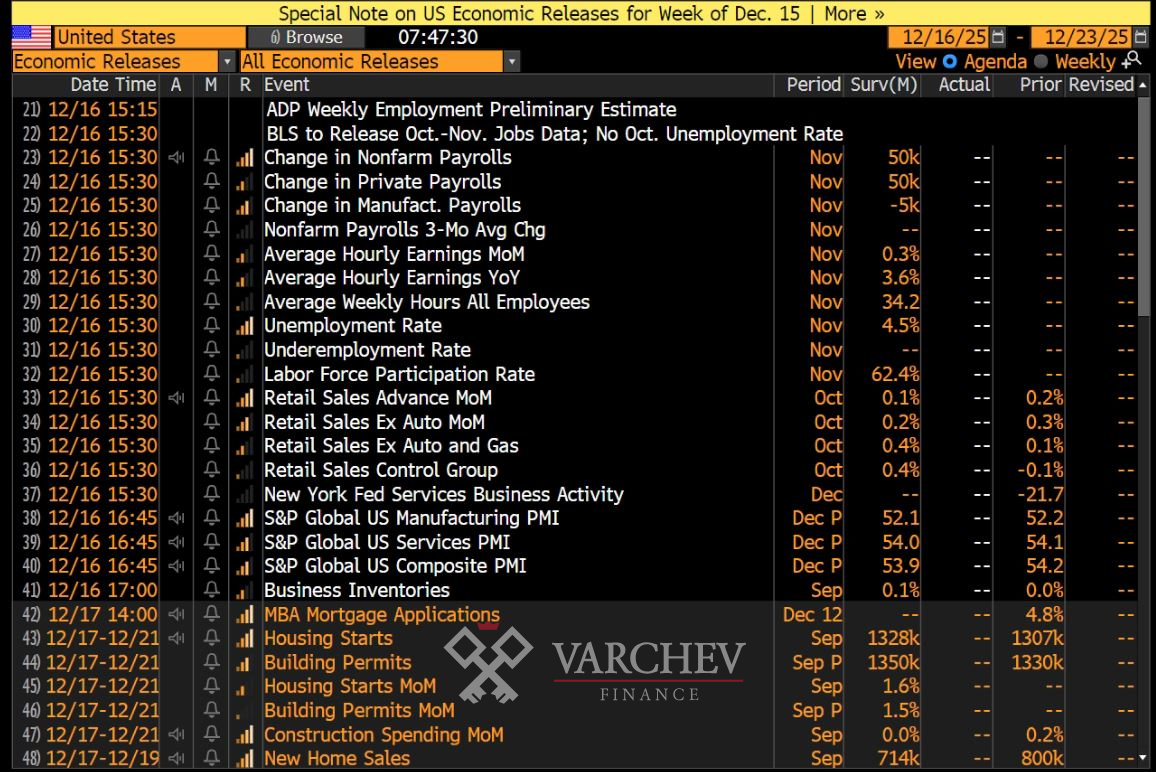
Today’s economic calendar is packed with important macroeconomic data from the euro area and the United States, which could have a significant impact on currency markets, equity indices, and overall market sentiment.
At 12:00, eurozone trade balance data for October will be released, with a surplus of around €19.4 billion expected. This indicator provides important insight into external demand and the competitiveness of the European economy.
At the same time, the ZEW Economic Sentiment Index for December will be published and is expected to reach 25.0 points. This indicator reflects the expectations of investors and analysts and is often seen as an early signal of future economic developments.
The main focus of the day will be on the United States, where key data on the labor market and consumer activity will be released between 15:15 and 15:30.
These include the ADP private-sector employment report, as well as the official Nonfarm Payrolls data for November, with expectations for an increase of around 119,000 new jobs. The unemployment rate is expected to remain unchanged at 4.4%, while the labor force participation rate is seen at around 62.4%.
Additional attention will be paid to average hourly earnings, a key indicator of inflationary pressure, with a projected monthly increase of 0.2% and an annual rise of 3.8%.
Retail sales data and the so-called retail control group will provide a clearer picture of the strength of consumer spending in October. At the same time, housing market data — building permits and housing starts — will be released, showing whether high interest rates continue to weigh on the property market.
Later in the afternoon, S&P Global will publish preliminary PMI indices for the manufacturing, services, and composite sectors for December. Expectations are for readings to remain above the 50-point threshold, signaling continued economic expansion.
The day will conclude with data on business and trade inventories, offering additional insight into the balance between supply and demand.
At 19:30, attention will turn to Canada, where Bank of Canada Governor Tiff Macklem will deliver a speech. Markets will closely monitor his tone for signals regarding future monetary policy and the outlook for interest rates.
Link to the full calendar:
https://calendar.varchevbrokers.com/calendar.php?lang=bg
Top 5 Things to Know Before Europe Opens
- Asian equity markets are declining alongside U.S. and European stock futures ahead of the key U.S. employment report for November. Shares in Hong Kong and South Korea are underperforming the region, as investors reduce risk ahead of the data release.
- The Japanese yen is strengthening against the U.S. dollar, becoming the best-performing G10 currency. The move comes amid growing expectations that the Bank of Japan could raise interest rates as early as this week. Elsewhere in Asia, the Chinese yuan is edging higher, while the Indian rupee has fallen to a record low.
- In the corporate sector, Ford Motor announced it will record costs of $19.5 billion related to a major restructuring of its electric vehicle business. Despite this, the company’s shares rose by about 1% in after-hours trading in New York.
- In Europe, Dutch pension fund PME is ending its relationship with BlackRock after concluding that the asset manager no longer acts in the fund’s best interests on issues such as climate risk. As a result, BlackRock will no longer manage an equity mandate worth around €5 billion.
- Oil prices are falling as markets closely watch prospects for a ceasefire in Ukraine. U.S. negotiators have proposed stronger security guarantees for Kyiv, increasing expectations of potential de-escalation. Additional pressure on prices is coming from a weakening forward curve in Dubai crude — another signal of rising global oversupply.
Forex Options Expiring Today
There is only one more important level worth paying attention to today, as highlighted in bold below.

This concerns EUR/USD at the 1.1750 level. These option expiries do not coincide with a specific technical level, but they have the potential to act as a “magnet” for price action, at least until key U.S. economic data are released later in the day.
Eurozone PMI data may introduce some volatility during the European session, but in the absence of surprises, a more subdued move in EUR/USD is likely until the release of the U.S. employment report and retail sales data.
European equities are expected to open in negative territory on Tuesday, reversing the gains seen at the start of the week.
The UK’s FTSE is expected to fall by around 0.25%, Germany’s DAX by 0.63%, France’s CAC 40 by 0.37%, and Italy’s FTSE MIB by 0.33%, according to IG data.
Investors in Europe are bracing for a busy week of key central bank decisions.
The final meeting of the year for the European Central Bank (ECB) will take place on Thursday. Interest rates are expected to remain at 2%, with ECB President Christine Lagarde noting that the central bank is likely to revise its economic growth forecasts higher again in December, after raising its annual GDP growth outlook to 1.2% in September.
The final monetary policy meetings of 2025 will also be held this week by the Bank of England, Riksbank, and Norges Bank. The Bank of England’s decision is expected to be finely balanced, though markets are pricing in a possible rate cut. Eurozone and UK inflation data will be released on Wednesday.
European leaders are also facing major challenges, as a summit in Brussels on Thursday will focus on financing for Ukraine. Among the topics under discussion is the potential use of billions of euros in frozen Russian assets to back a €210 billion ($246 billion) loan for Kyiv.
Asia-Pacific markets posted declines overnight, tracking losses on Wall Street, as investors continue to rotate out of the artificial intelligence sector.
In the United States, stock futures traded near flat levels on Monday evening, as markets await the release of the November employment report.
Economists surveyed by Dow Jones forecast that Nonfarm Payrolls will show an increase of 50,000 jobs, significantly lower than the 119,000 added in September. The unemployment rate is expected to tick up slightly to 4.5% from 4.4%. U.S. retail sales data for October are also due to be released.
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment