


Today’s Economic Calendar
Today’s economic calendar is relatively busy, with the focus on manufacturing PMI data from Europe, the U.K., and the U.S., as well as several speeches by central bankers. In Europe, the manufacturing indices for France, Germany, and the Eurozone are expected to remain around previous levels — 48.3, 49.6, and 50.0, respectively — which would confirm sector stabilization but without clear growth.
For the U.K., the forecast stands at 49.6, unchanged from the previous month. Later, attention will shift to the U.S., where the S&P Global Manufacturing PMI and especially the ISM Manufacturing PMI will be released — the main focus for markets today. Expectations point to a slight improvement to 49.4, while investors will closely monitor the employment and prices components to assess the state of the industrial sector and potential inflationary risks.
Additionally, remarks from officials of the ECB, Fed, Bundesbank, and Bank of Canada are scheduled throughout the day and could bring additional volatility to market movements.
Forex Options Expiring Today
USD/JPY option expiries remain heavily concentrated around the 150 level — a key psychological and technical area that continues to act as a magnet for price action.
EUR and GBP also show significant interest around 1.1450 and 1.3100, respectively, which may keep movements range-bound until the New York close.
Major Option Expiries:
- EUR/USD: 1.1450 (€771.9M), 1.1400 (€686M)
- USD/JPY: 150.00 ($1.13B), 152.50 ($401.3M), 151.50 ($385.4M)
- AUD/USD: 0.6600 (A$338.6M)
- GBP/USD: 1.3100 (£468M), 1.3350 (£372.1M)
- EUR/GBP: 0.8775 (€300.3M)
- USD/MXN: 18.60 ($355.9M)
Overall, the strongest interest is around USD/JPY 150.00, which is likely to keep the pair hovering near that level before expiries.
Top 5 Things to Know Before European Markets Open
- Asian equities rose, led by gains in South Korea, while both U.S. and European futures traded in positive territory. The CSI 300 index lagged behind regional peers. A private survey showed that China’s manufacturing activity expanded more slowly than expected in October.
- The White House announced that China will effectively halt the implementation of additional restrictions on rare earth exports and end investigations into U.S. semiconductor firms.
- Oil prices climbed after OPEC+ announced plans to pause production increases in Q1 2026, following another modest hike planned for next month. Meanwhile, President Trump threatened possible U.S. military action in Nigeria against Islamist militants if the government fails to stop “the killing of Christians.”
- Bitcoin declined, along with Ether and Solana, while gold edged higher after an initial drop that followed China’s decision to remove a tax incentive.
- The French government will begin closed-door talks with lawmakers in an effort to save the budget after sharp parliamentary disputes threatened Prime Minister Lecornu’s position. In the U.K., Chancellor of the Exchequer Reeves is considering tax hikes, including a levy on wealthy Britons moving abroad and higher taxes on luxury properties, as part of preparations for the upcoming budget.
European Markets Expected to Open the Week in Positive Territory
European stock markets are expected to start the new trading week — and the new month — on a positive note ahead of a busy week featuring central bank decisions and corporate earnings.
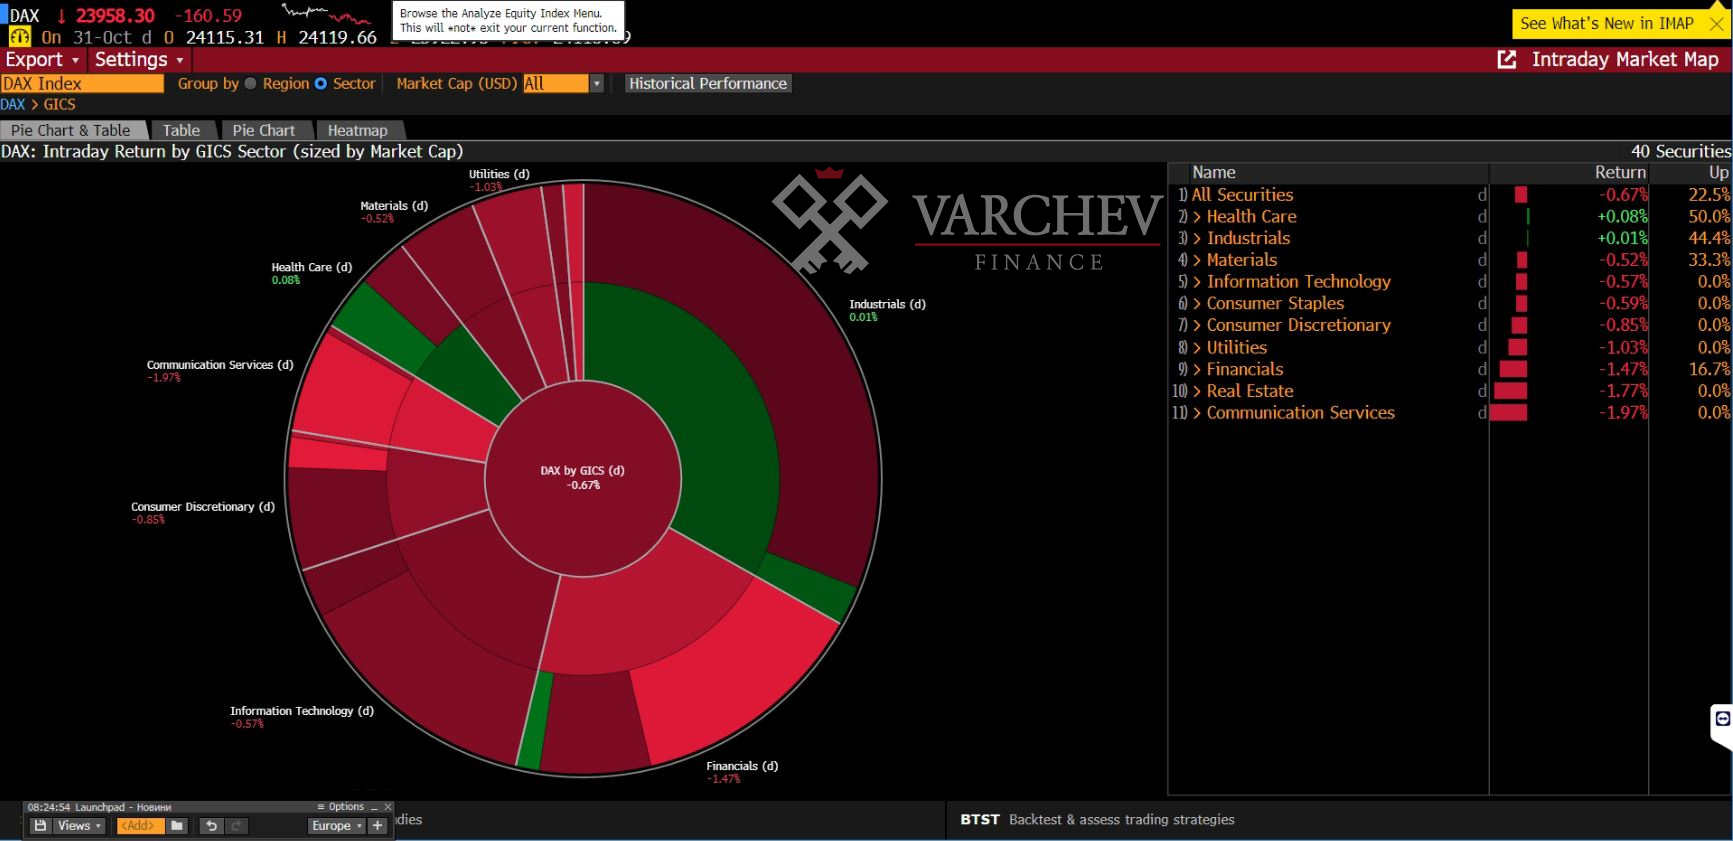
According to IG, FTSE 100 is set to open up 0.16%, DAX up 0.27%, CAC 40 up 0.3%, and FTSE MIB up 0.12%.
This will be a busy week for corporate earnings in Europe. Ryanair reports Q3 results on Monday, followed by BP, Ferrari, and Aramco on Tuesday, and BMW and Vestas on Wednesday. Commerzbank, Diageo, Rheinmetall, AstraZeneca, and Maersk will report on Thursday, while Richemont will close the week on Friday.
On the central bank front, Sweden’s Riksbank will announce its interest rate decision on Wednesday, followed by the Bank of England on Thursday, with economists divided on whether it will hold or cut rates. Bundesbank in Germany will also release its latest financial stability report.
U.S. futures were little changed Monday morning, while Asia-Pacific markets traded mixed.
Investors in Asia analyzed the latest data on China’s manufacturing activity following the release of the RatingDog index for October. The manufacturing PMI slowed to 50.6, below expectations of 50.9 and September’s 51.2.
Official PMI data released Friday by China’s National Bureau of Statistics showed that manufacturing activity in October contracted to 49.0 — the lowest level in six months.
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment