


Today’s economic calendar is packed with key releases, with the main focus on the ADP Nonfarm Employment Change data in the U.S., widely seen as a leading indicator ahead of Friday’s Nonfarm Payrolls. The results will offer an early look at the state of the labor market and could significantly influence expectations for the Federal Reserve’s policy outlook.
From Europe, a series of PMI indices are expected — France, Germany, and the eurozone will publish their final October readings, which will show whether activity in the services sector is stabilizing after recent months of weak growth. Germany will also release factory orders for September, providing insight into the health of the industrial sector. In the UK, services and composite PMI data will indicate whether the economy is managing to stay above the growth threshold.
In the afternoon, investors will watch for U.S. data on PMI, factory orders, ISM Non-Manufacturing, and JOLTS, which, together with ADP, will paint a fuller picture of economic activity and employment. Later in the evening, U.S. President Donald Trump and Bank of Canada Governor Tiff Macklem are scheduled to speak — events that could add extra volatility to the markets. The key focus of the day remains the U.S. labor market data and its potential impact on the dollar and future rate-cut expectations.
Top 5 things to know before European markets open
- Asian markets fell amid concerns over lofty tech valuations, though some losses were trimmed later in the session. U.S. index futures are also lower after major indices declined on Tuesday. Gold and bonds rose on safe-haven demand.
- Advanced Micro Devices (AMD) shares dropped in after-hours trading after the company’s Q4 revenue forecast of $9.6 billion failed to impress investors. While above analysts’ consensus of $9.2 billion, expectations had reached as high as $9.9 billion, disappointing the market.
- President Donald Trump said he met with representatives from Switzerland, and that further trade negotiations will take place. Meanwhile, Bundesbank President Joachim Nagel urged European governments to pool defense resources and cede some national authority to enable joint financing.
- In the U.S., the Democratic Party scored its biggest political victories since losing to Trump a year ago, winning elections in Virginia, New Jersey, and New York. Zohran Mamdani was elected as the 111th Mayor of New York City.
- In Canada, budget deficits are expected to rise under Mark Carney’s leadership, totaling CAD 167.3 billion over the next five years. The increase is driven by higher public spending on capital projects and weaker tax revenue forecasts.
European markets set for lower open amid global tech sell-off
European stocks are expected to open lower, following a global market downturn as concerns grow over stretched valuations in technology shares.
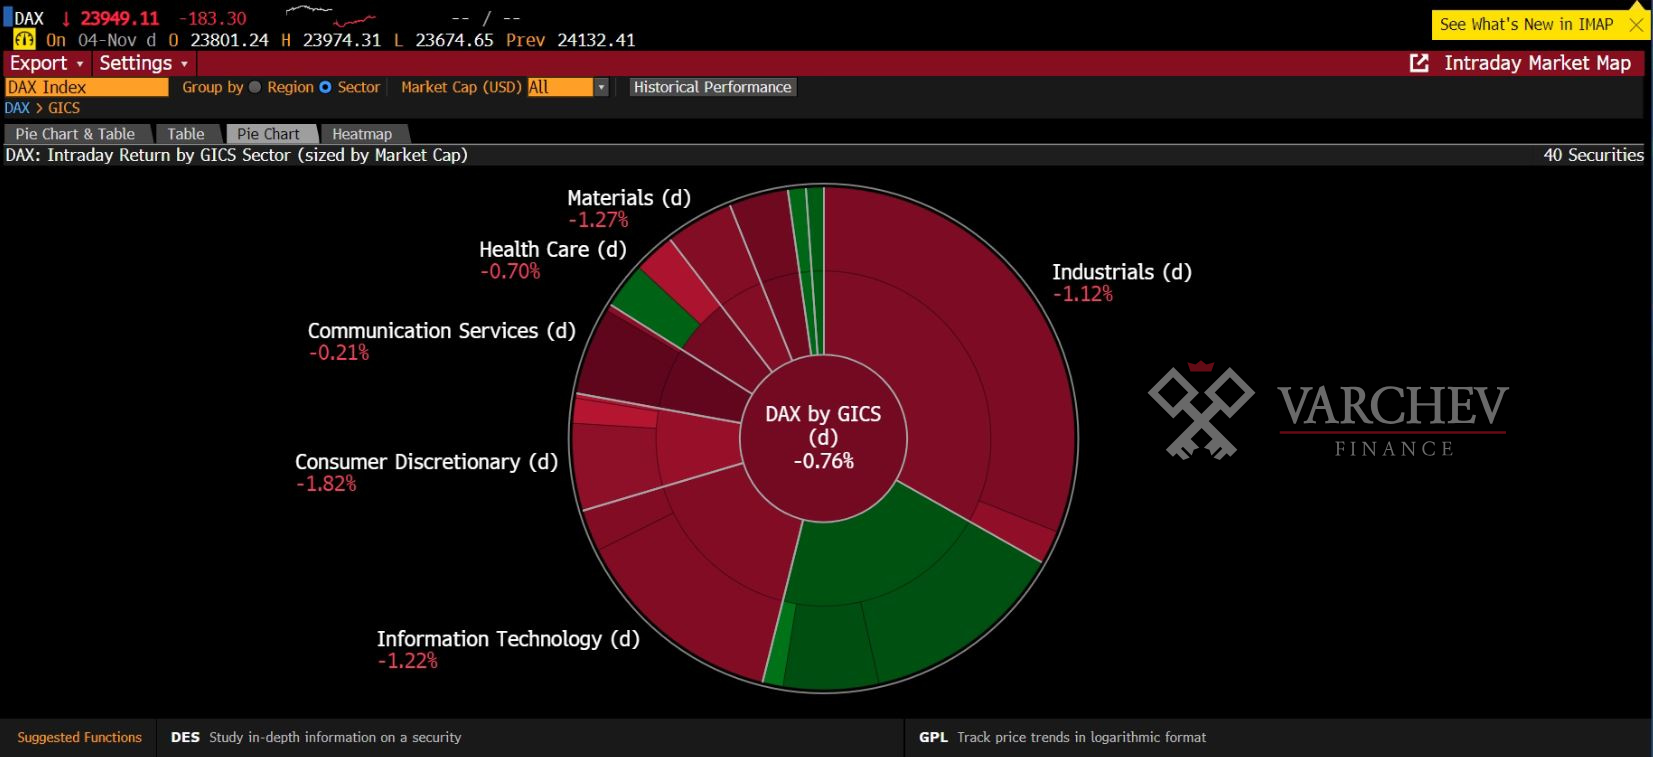
According to IG data, the UK’s FTSE is set to open 0.27% lower, Germany’s DAX down 0.62%, France’s CAC 40 off 0.56%, and Italy’s FTSE MIB down 0.76%.
The weak tone in Europe on Wednesday reflects similar sentiment in the U.S. and Asia-Pacific, where investors are increasingly worried that AI-related stock valuations could be forming a bubble.
Overnight, Nasdaq futures declined as markets continued to waver over the outlook for major tech names. Meanwhile, Japan’s Nikkei 225 fell below the 50,000-point mark, tracking a broader sell-off across Asia driven by capital outflows from AI-linked equities.
Market sentiment also took a hit after the CEOs of Goldman Sachs and Morgan Stanley warned investors to brace for a potential market correction over the next two years.
Today is a busy day for corporate earnings in Europe, with Novo Nordisk, BMW, Leonardo, Orsted, and Vestas all reporting third-quarter results.
Later, the Swedish central bank (Riksbank) will announce its latest interest rate decision, while Germany’s factory orders, UK new car registrations, and eurozone PMI data will also be released.
Forex options expiring today
There is only one notable factor worth paying attention to, highlighted below in bold.

This refers to the NZD/USD options at the 0.5675 level. However, these expiries are not expected to have a significant impact on the market, as they are not tied to any key technical level. Moreover, the overall market sentiment and risk appetite remain the main forces driving trading this week, which is currently of greater importance to traders.
At the moment, there is a slight improvement in risk appetite ahead of the European session. This is helping to bring some stability to the markets and a modest recovery in Antipodean currencies. AUD/USD is steady around 0.6490, while NZD/USD is up 0.2% at 0.5653, after earlier touching a daily low of 0.5630.
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment