


Dutch trading specialist Karel Mercx published the following commentary, in which the inverted value (multiplied by –1) of the silver swap rate minus U.S. interest rates can be used as a proxy for the implied silver lease rate in order to identify physical tightness in the London silver market:
“ The 1-year silver swap minus the U.S. interest rate is now at –7.18%.
This distortion explains why the rally in silver is not over.
Only at the blue-green line do supply and demand normalize.”
Six days earlier, Mercx published the following comment:
“ The 1-year silver swap minus the U.S. interest rate is now close to –7%! This distortion is the key reason why the silver rally is not finished.
This spread should normally be positive, since silver needed one year from now carries costs for storage, insurance and financing.
Further explanation.
The silver swap rate is a core component of the global precious metals trade. It exists because large participants such as banks, producers, industrial users and investors constantly exchange silver for dollars without physically moving the metal from vault to vault. This mechanism keeps the London physical market tightly linked to the New York financial market.
But this system is now under stress. Physical silver today is almost 7% more expensive than silver for delivery one year ahead. Swaps were designed to avoid transporting metal around the world, but today silver is actually being moved because buyers are demanding physical delivery.
Holding physical silver is neither easy nor cheap.
A position worth $1 million weighs several hundred kilograms, spread across dozens of heavy bars that require vault space, insurance and security…
…This issue is now being priced in by the market. As long as the 1-year silver swap minus U.S. interest rates remains below the blue-green line, upward pressure on the silver price will continue. No one knows exactly where supply and demand will meet again.”
“I added a trend arrow to the chart that Mercx published.”
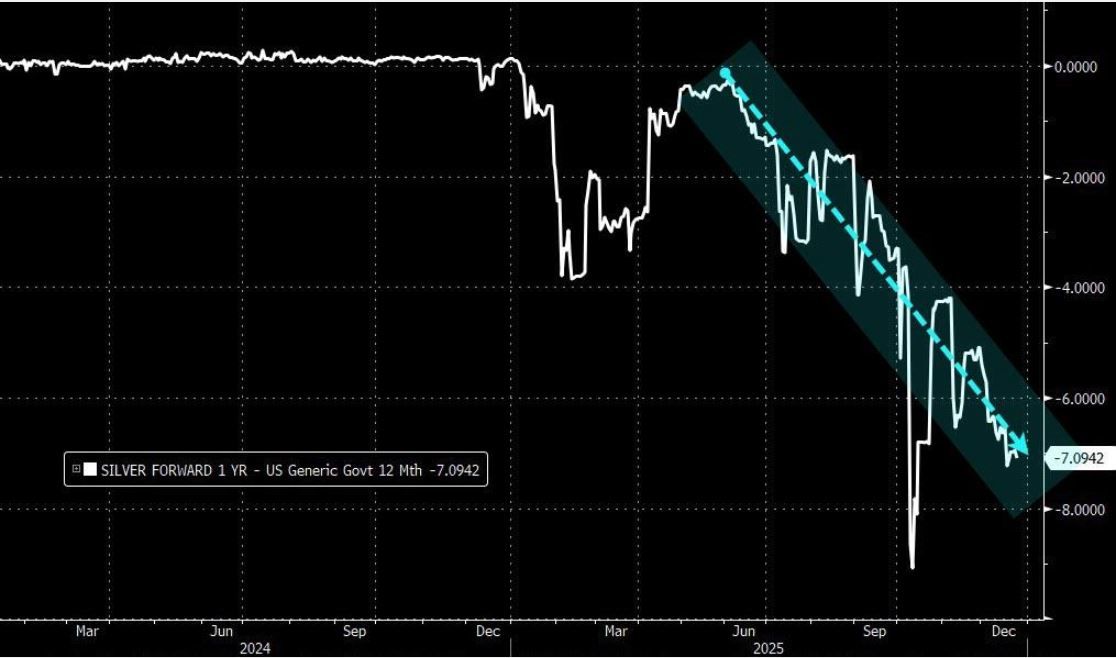
Figure 1 – 1-year silver swaps minus 1-year U.S. interest rates as of December 23, 2025.
Note that the distance from the red normalization line is widening as the silver shortage in London deepens. The London silver market is deteriorating (breaking down), not stabilizing.
[ZH: the spread between SHFE and COMEX silver futures is, to put it mildly, extreme — which is encouraging silver flows from London to Shanghai]…
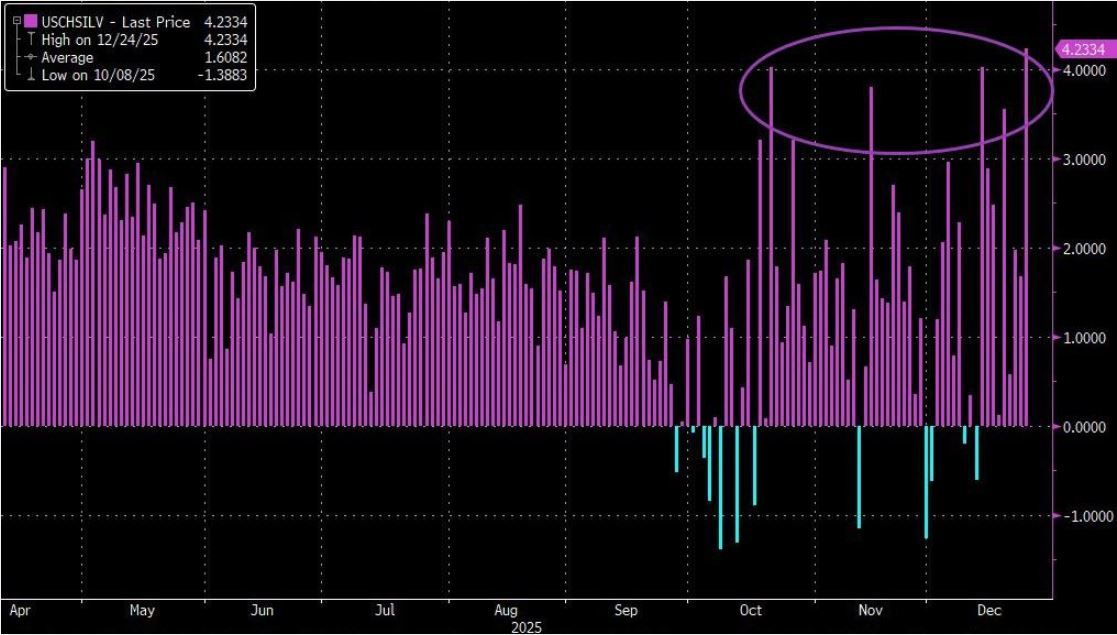
This is what a “panic run” on the London physical silver market looks like, where holders of unallocated silver ownership and delivery claims, at the margin, begin to demand actual physical delivery of the metal.
The enormous leverage of London’s paper (synthetic or “vapor”) claims relative to the physical silver available for delivery creates the potential for a very rapid and abrupt unwind of the London market.
Varchev Absolute Trader
борсова платформа
- Търгувай над 3000 финансови инструмента: Crypto, Форекс, Акции, Индекси, Суровини, ETF-и
- Използвай платформа с директно изпращане ордерите на борсите
- Cloud base платформа - твоят трейдинг сетъп на всяко устройство
- Market Sentiment - търгувай с настроенията на инвестиционите банки
- Top movers - най-горещите трейдове във всеки един момент
- Stocks scanner - филтрирай най-подходящите за твоя трейдинг стил пазарни инструменти
- Heat map - Търгувай в посоката на големите играчи
Meta Trader 5
- Търгувай Crypto, Форекс, Акции, Индекси, Суровини - всичко на едно място
- Автоматизирана търговия с интелигентни стратегии и роботи (Expert Advisors)
- Разширен технически анализ с хиляди индикатора и инструменти
- Сигурност и стабилност – платформа, доверена от милиони по света
- Нулев марджин при насрещни/хеджирани позиции
- Без комисиона при търговия със CFDs
- Светкавично изпълнение на сделките
Read more:

Login to comment
Comments:
Leave a comment